In the Middle of a 10 Year Term? You Have Options!
Bill Fraser • July 2, 2019

If you bought a house, or had a mortgage renew roughly five years ago, there's a chance the struggling economy and the relatively low interest rate environment (at the time) influenced you to "play it safe" and lock in a mortgage term for the next ten years. Because, at the time, it seemed like interest rates couldn't go any lower and the difference in the interest rate between the five year fixed term, and the ten year fixed was negligible. Five years extra security made a lot of sense.

Without the benefit of a crystal ball, this looked like a good decision. However, unfortunately as interest rates have dropped even further, you're probably now stuck in a mortgage with a rate that is higher than what is currently being offered on the market. If you are second guessing your original decision. Don't. You made a decision based on the information you had at the time, if rates would've gone up, you'd be in a great place now. But, as that isn't the case, the best we can do is look for a silver lining, and here it is, did you know that there is a mandatory fine print clause in your ten year contract that might help you save money over the next five years?

After the first five years of a ten year term has been completed, the penalty to break the mortgage is three months interest, instead of the interest rate differential penalty. That's a really big deal!
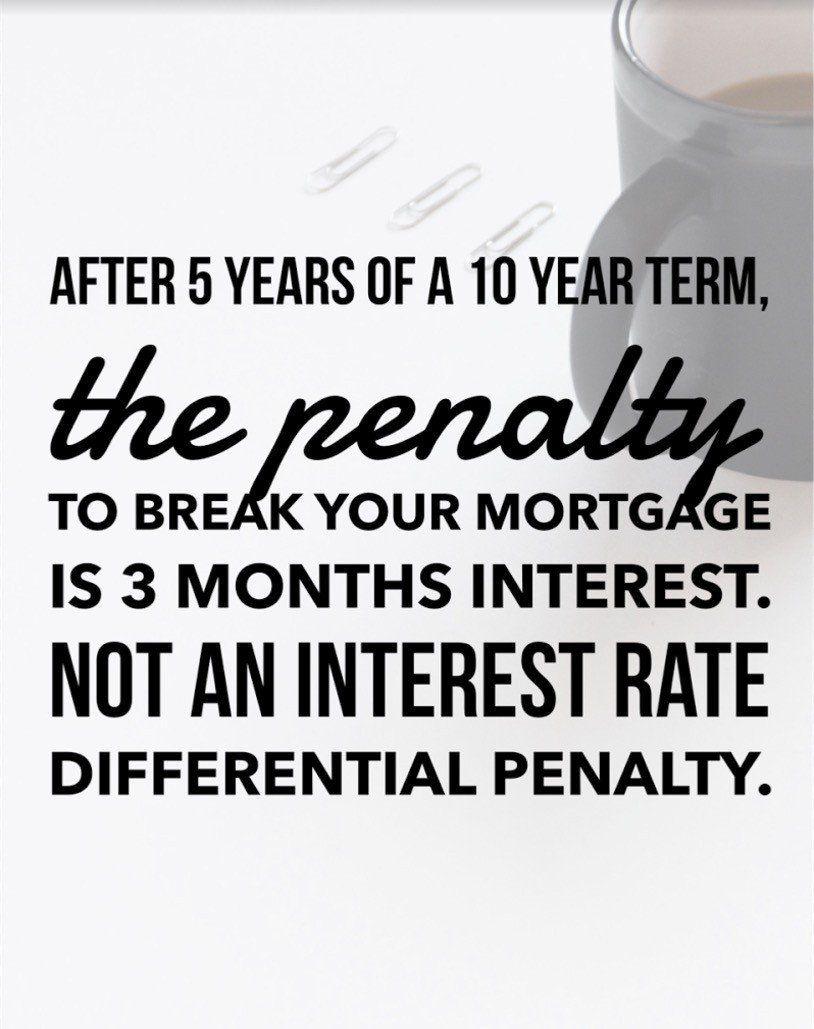
It doesn't matter which lender you are with, this is actually a law in Canada, and not conditional upon the contract you signed with your lender. So, if the thought of an outrageous penalty has been keeping you from looking at all your options, you should really check out what is available on the market today.

Interest rates are really low, so low in fact that there's a chance you can switch out of your ten year rate into another mortgage product at a lower rate and not only cover the cost of the three month interest penalty, but actually be further ahead only a couple years into your new term. The real goal is to save thousands of dollars by switching, and that is very possible!

As each person's financial situation is different, rather than going through a hypothetical situation where we explain how this all works for hypothetical people, if you have made it this far, chances are this applies to you. You should really reach out and contact me to see about all your options, because you have options!.

There's no cost for my services, so let's see how much money you can save over the next five years!

BILL FRASER
OWNER / MORTGAGE EXPERT

BOOK AN APPOINTMENT CONTACT ME
RECENT POSTS

By Bill Fraser • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Bill Fraser • October 27, 2026
You’ve found the right home, your offer’s been accepted, and your financing is approved—congratulations! But before you can pick up the keys and celebrate, there’s one more important stage: the closing process. Closing is the final step in your homebuying journey, where all the paperwork, legal details, and financial transactions come together. It can feel overwhelming if you don’t know what to expect, but with the right preparation, closing can be smooth and stress-free. Here’s a step-by-step guide to help you understand the process. Step 1: Hire a Lawyer or Notary A real estate lawyer (or notary, depending on your province) handles the legal side of closing. They will: Review the purchase agreement and mortgage documents Conduct a title search to confirm the seller has the legal right to sell the property Ensure the mortgage lender is properly registered on the title Handle the transfer of funds between you, the lender, and the seller Your lawyer or notary will be your main point of contact during closing, so choose one you trust and who communicates clearly. Step 2: Finalize Your Mortgage Your lender will send the mortgage instructions directly to your lawyer or notary. At this stage: You’ll provide proof of property insurance (lenders require this before releasing funds) You’ll confirm your down payment and closing costs are available in your lawyer’s trust account The lawyer will prepare all documents for your review and signature Step 3: Pay Closing Costs Closing costs typically range from 1.5% to 4% of the purchase price. These can include: Legal fees Title insurance Land transfer tax (where applicable) Adjustments for property taxes or utilities prepaid by the seller Home inspection or appraisal fees (if not already paid) Your lawyer will provide a final statement of adjustments so you know exactly how much is due on closing day. Step 4: Sign the Paperwork A few days before closing, you’ll meet with your lawyer or notary to sign all the necessary documents, including: Mortgage agreement Title transfer Insurance confirmations Statement of adjustments Bring valid government-issued ID to this appointment. Step 5: Transfer of Funds On the day of closing: Your lender sends the mortgage funds to your lawyer Your lawyer combines these funds with your down payment and pays the seller Legal ownership of the property is transferred into your name The lender is registered on title as a secured creditor Step 6: Get the Keys! Once the paperwork is filed and the funds have cleared, your lawyer will confirm that the transaction is complete. You’ll then get the keys to your new home—officially making it yours. The Bottom Line The closing process is a series of important steps, but with the right team in place, it doesn’t have to be stressful. By working closely with your mortgage professional and lawyer, you’ll have guidance every step of the way—from signing the documents to turning the key in the front door. If you’d like help preparing for the closing process—or want a clear breakdown of your own closing costs— connect with us today.